Risk, hedge accounting & valuations

Hedge accounting and risk reporting, handled.Every reporting period.

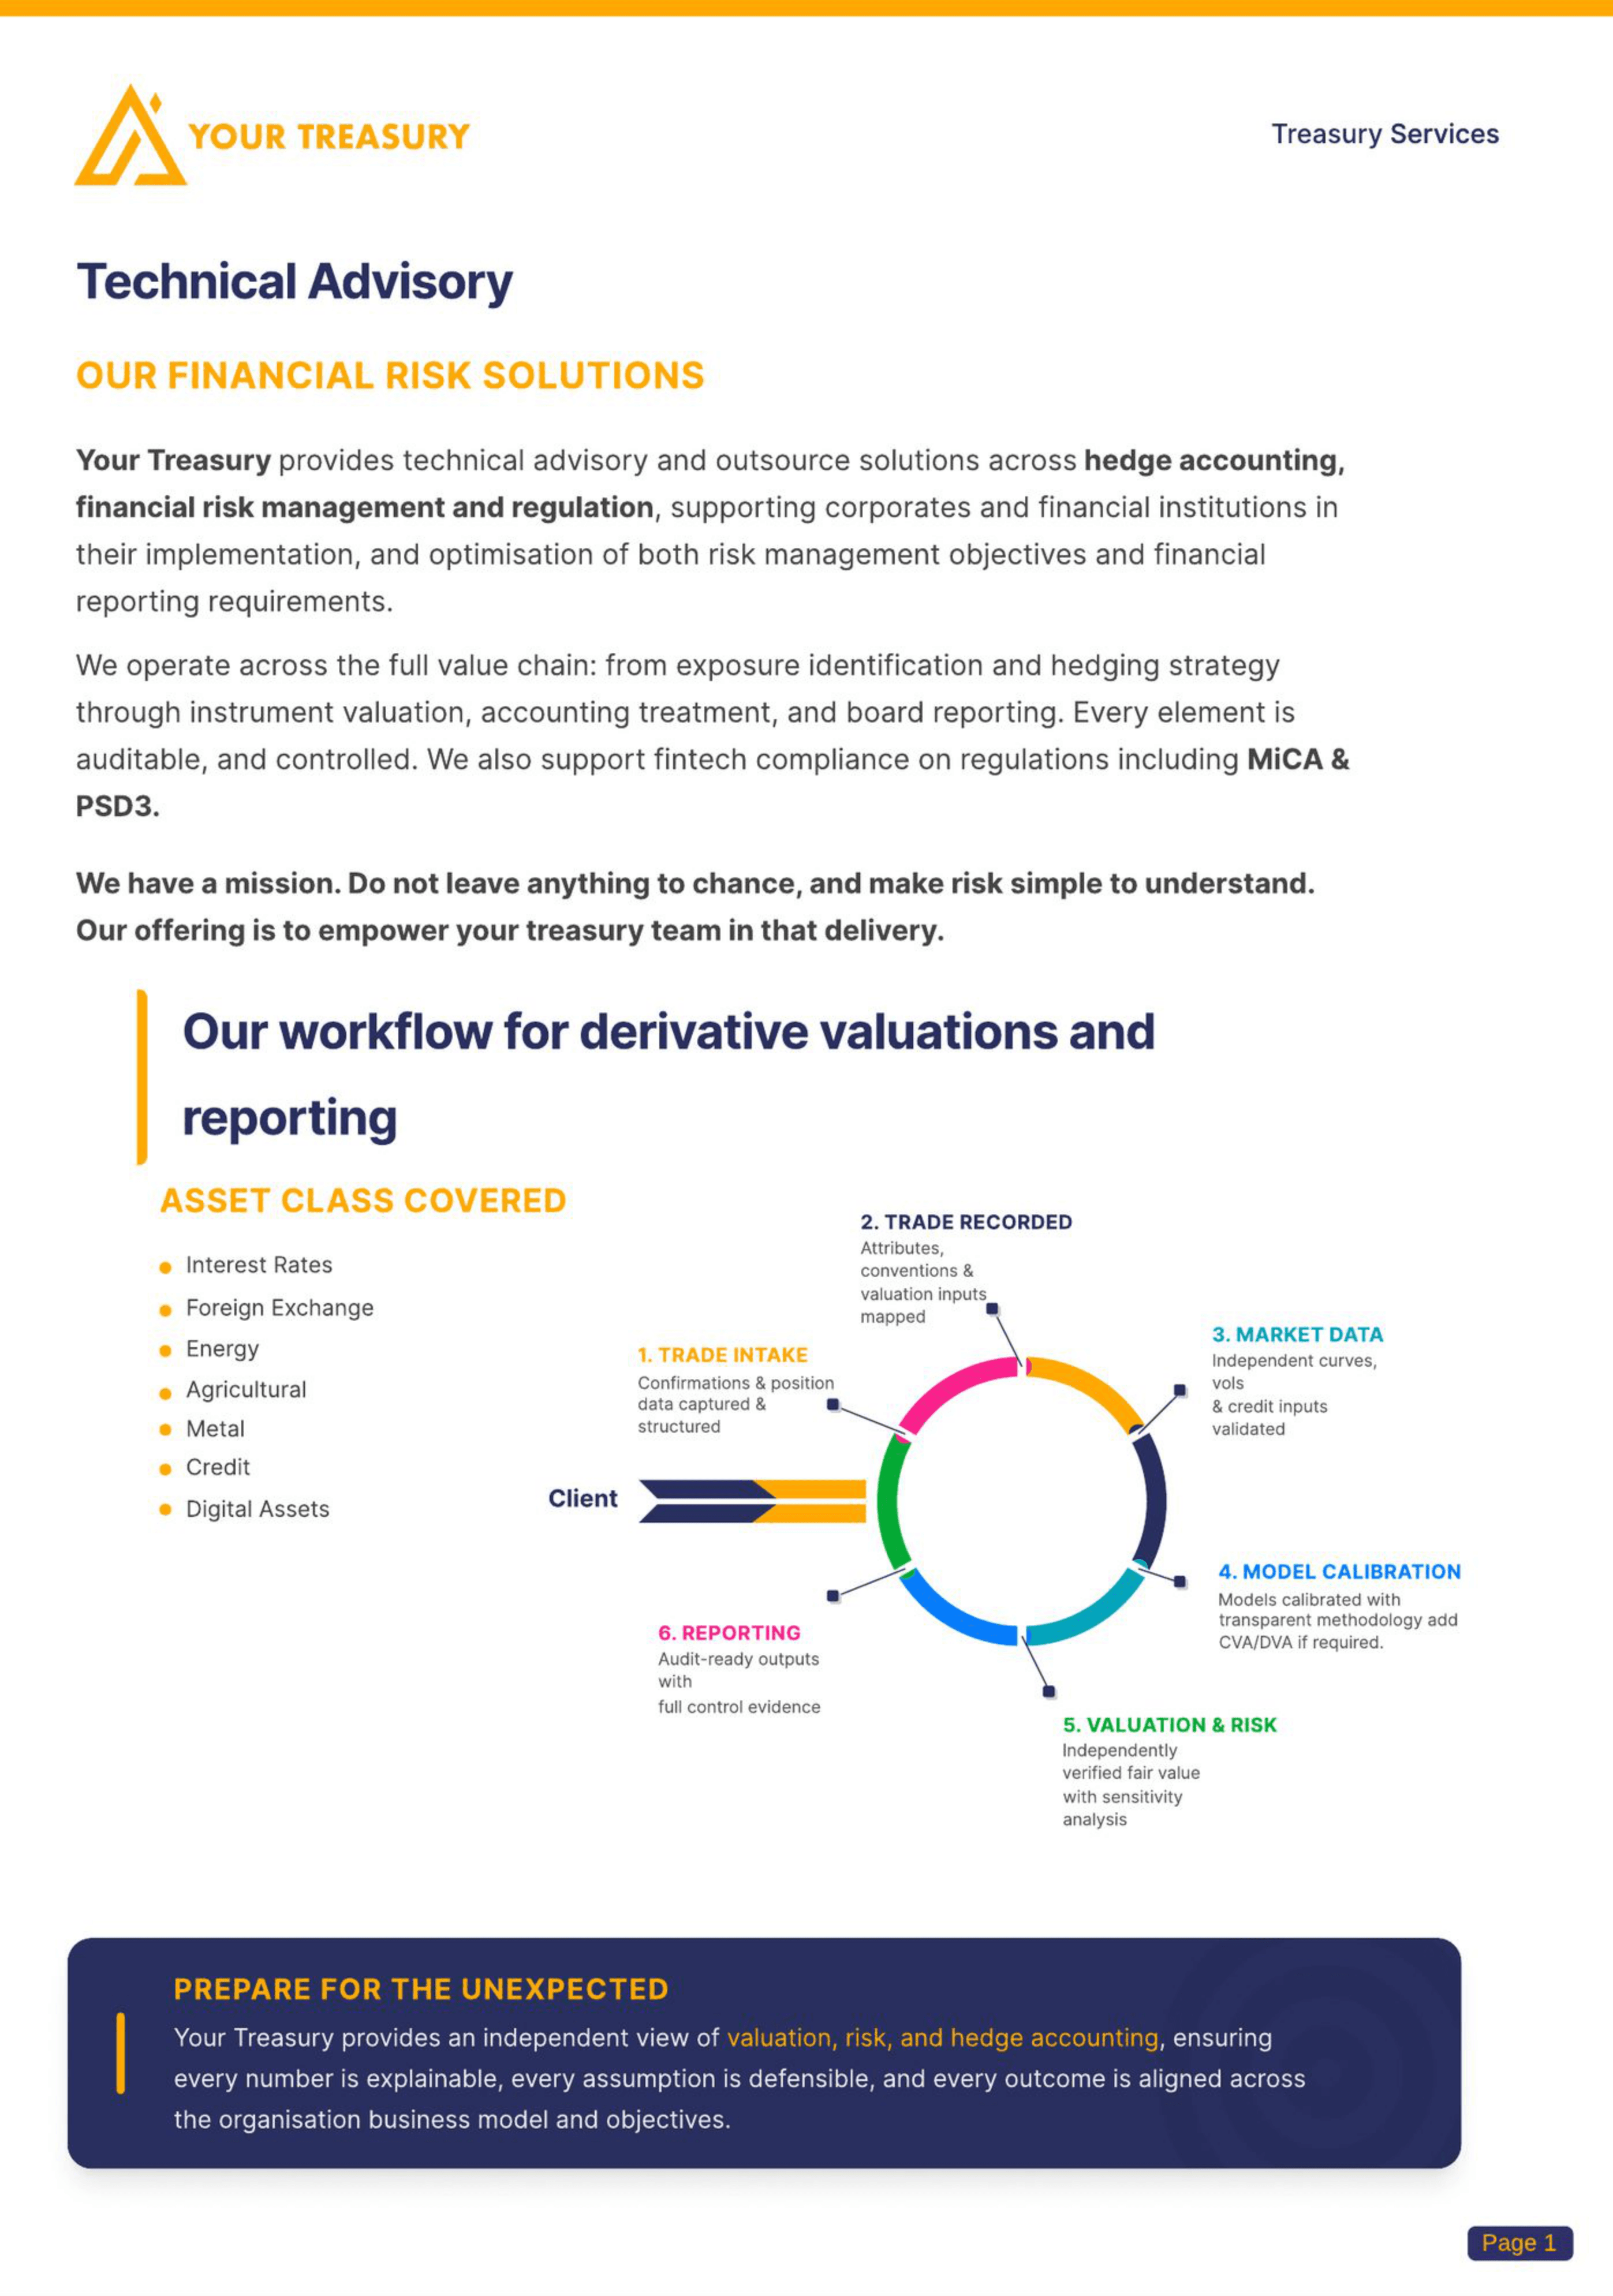
Hedging policy, VaR and Cash Flow at Risk, hedge accounting under IFRS 9 and ASC 815, and independent derivative valuations, for corporate treasuries and banks.

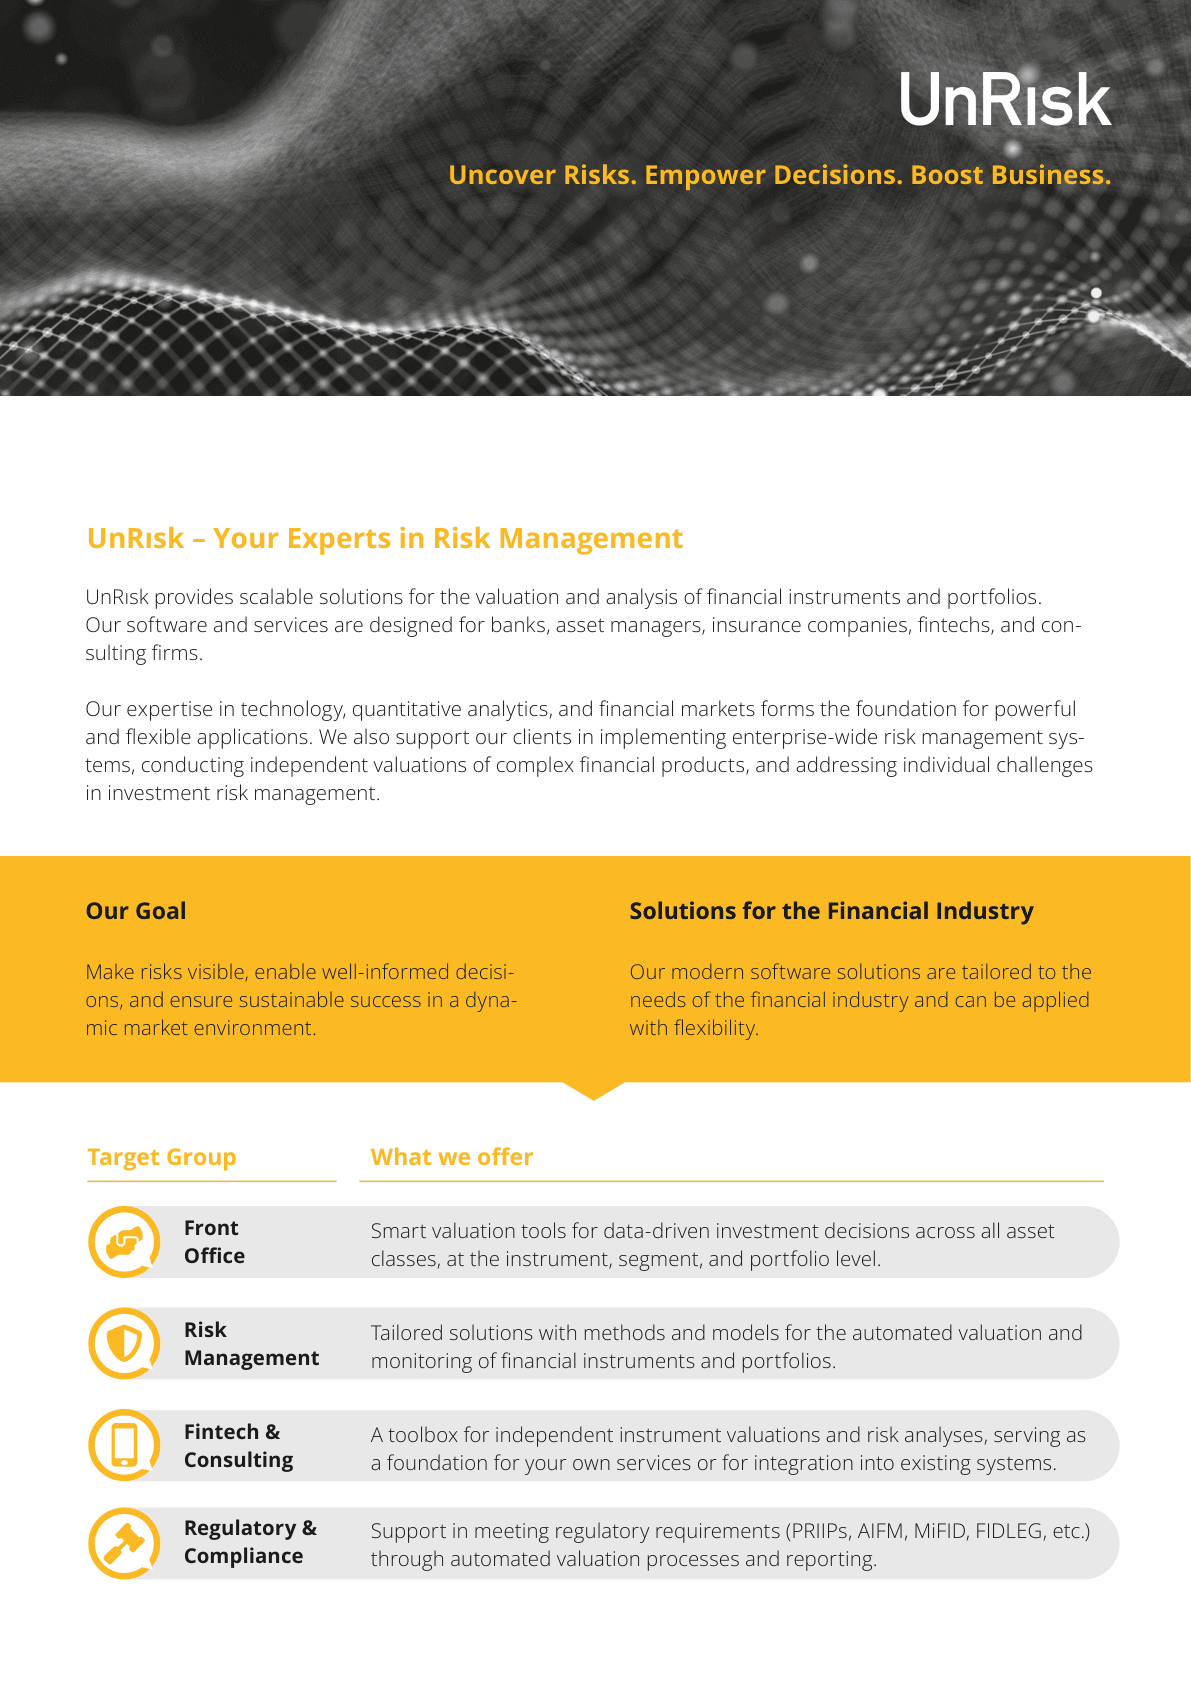
Valuations run on UnRisk, the engine also used by

  • Raiffeisen Capital Management
  • Moody's
  • Volksbank
  • KPMG

Every reporting period

Hand over the reporting, keep the control.

Your policy, your sign-off, our production work and audit evidence. The same six outputs every period, for corporates and financial institutions alike.

How our hedge accounting service works →
Valuations
Independent mark-to-market and XVA on every reporting date.
Hedge effectiveness
Effectiveness testing each period, with rebalancing where needed.
Scenario analysis
Stress and sensitivity scenarios on the hedges, the P&L and the balance sheet.
Hedge documentation
Designation packs and the hedge documentation library kept current.
GL entries
Journal entries ready to post to your general ledger.
Custom reporting
Reports in your format, fed into your BI tools and board packs.
  • ISO 27001
  • SOC

Reporting produced to ISO 27001 information security and SOC control standards, with the evidence your auditors expect.

Month-end made simple

We embed within your reporting cycle, supporting you through strategy, periodic reporting and audit. Over time we transfer knowledge and capability into your treasury team, with full handover of our ISO-certified valuation solution whenever you're ready to bring it in-house.

Instrument coverage

From vanilla to structured.

End-to-end fair value calculations across all asset classes. Every number is explainable and every assumption is defensible.

  • Interest rates
  • Foreign exchange
  • Energy
  • Agricultural
  • Metal
  • Credit
  • Digital assets

Interest rate and structured

  • Swaps, swaptions, caps, floors
  • Callable and cancellable, CMS-linked
  • Cross-currency and hybrids

Foreign exchange

  • FX forwards, swaps, options
  • NDFs, participating forwards, barriers
  • Path-dependent and multi-leg structures

Commodities

  • Energy, metals, agricultural
  • Structured products with optionality
  • Cross-commodity exposures

Credit and structured finance

  • Credit derivatives
  • Credit-linked notes
  • Hybrid structures

Equity and hybrid

  • Equity options and structured products
  • Multi-asset hybrids

Embedded options

  • Identification within contracts
  • Separation and valuation under IFRS / US GAAP

What we do

Two services. One practitioner team.

Hedge accounting first, then the risk measurement, transformation and automation behind it. The same practitioners carry the work from design through to the numbers in your accounts.

01

Hedge Accounting Services

Hedge accounting, derivative valuations and scenario analysis, run every reporting period inside your governance.

  • Hedge accounting under IFRS 9, IAS 39 and ASC 815
  • Independent derivative and XVA valuations
  • Scenario analysis and disclosure-ready output
  • Macro hedging for banks under the IAS 39 carve-out
02

Treasury Risk Transformation & Solutions

We advise and we build: policy, risk measurement and reporting in your systems, then AI hedging and UnRisk-powered valuation to automate it. Supported by market-leading financial engineers.

  • Cash Flow at Risk and Value at Risk
  • Commodities and basis risk
  • Lease residual values
  • Risk diagnostic, policy and hedging framework
  • AI agents that propose hedges, with a human approving every trade
  • Derivative and financial risk valuation with UnRisk

The practitioners

The people you meet do the work.

Meet the whole team →
Dominic Lynch

Dominic Lynch

Co-Founder

A group treasurer recognised for his work in derivatives, digital assets and financial risk management. Has consulted on IBOR reform, IFRS 9, dynamic risk management and asset-liability management.

James Kelly

James Kelly

Co-Founder

An accomplished FTSE 100 treasurer with a track record at Pearson, Sky and Kingfisher. Holder of the Adam Smith, Alexander Hamilton and TMI awards.

Helmut DeGraff Mayer

Helmut DeGraff Mayer

Senior Risk & Strategy Advisor

20+ years across the IMF, HSBC, American Express and Ernst & Young. Has served as a regulator-approved CRO and built enterprise risk and risk appetite frameworks.

Michael Aichinger

Michael Aichinger

Managing Partner, UnRisk

Quantitative risk and financial engineer behind the UnRisk valuation engine that our valuations, VaR and XVA run on. Co-author of our CFaR paper.

Cash Flow at Risk

The three questions a board asks

Trading-desk VaR asks how much could be lost on today's positions over a short horizon. Boards are asking how volatility hits the business over the months and years it takes to change course.

  1. 1

    How much of our performance is at risk?

    Not the loss on open positions, but how profitability and cash flow will evolve over the horizon the business plans against. The distribution, not a worst-case estimate.

  2. 2

    How do risks aggregate across the portfolio?

    Which factors contribute most, and where natural offsets already exist. Every material driver in one distribution, then decomposed.

  3. 3

    How does risk depend on the choices we make?

    How Cash Flow at Risk changes if an investment is delayed, hedging is restructured or the balance sheet is reshaped. A decision-support tool, not a monitoring report.

How we deliver

A live CFaR programme on your real portfolio in under a week.

UnRisk's production-grade derivatives and risk library, combined with practitioner-led diagnostics, a turnkey deployment, and integration into the workflows and BI stack your team already uses.

  1. 01

    Diagnose

    Fine-tune and advise

    Exposure discovery, a diagnostic of the current hedge programme, policy gap analysis and confidence-level calibration, before a single line of code is written.

  2. 02

    Deploy

    Turnkey build and report walk-through

    UnRisk provisioned in the cloud or on-premise, exposures loaded, first Monte Carlo run produced. We walk leadership through the numbers line by line and co-author the refreshed hedging policy.

  3. 03

    Integrate

    Workflows, BI reporting and data lakehouse

    Outputs flow into the TMS, board packs and BI layers. Scheduled jobs run mark-to-market, CFaR, hedge effectiveness and ratio optimisation with ASC 815 / IFRS 9 audit trails.

By the numbers

Practitioner-led, measurable outcomes

The practitioners you meet do the work. They have run treasury risk and hedge accounting inside corporates and banks.

FX volatility
80%
Reduction in unhedged P&L exposure
Years delivering
20+
Combined practitioner experience
Awards
8
Adam Smith, TMI, Alexander Hamilton & more

Why practitioners

Not the large-firm model

Who does the work

Typical:Senior people sell it, a leveraged team delivers it.

The practitioners you meet do the work. They have run treasury risk and hedge accounting inside corporates and banks.

Independence

Typical:If the firm audits you, independence rules can limit the design and valuation work it may take on.

We don't audit. We can design the hedge, run the accounting and value the book.

Advice and delivery

Typical:A recommendations report, then the hand-off back to your team.

We advise and we build, then run the reporting each period if you want us to.

Valuations

Typical:Often a separate team, with a separate engagement and fee.

Independent valuations and XVA in the same engagement, powered by UnRisk.

Speed

Typical:Large programmes with long mobilisation.

First results in weeks, inside your existing systems, with an automation plan for what follows.

Independence

We don't audit. We can design the hedge, run the accounting and value the book.

Specialised advisory

Where the standard close isn't enough.

Our team has participated in regulatory reform and transition adjustments for over a decade, and has worked on exotic topics across the corporate and banking industry.

Component hedging of commodities
Isolate the hedgeable risk within commodity input costs: protecting manufacturing margins, qualifying for hedge accounting, and keeping price swings out of P&L.
Dynamic hedging under IAS 39
Managing dynamic portfolios and macro-hedging strategies for banks while maintaining strict compliance with IAS 39 documentation requirements.
Transition to RMA
The IASB's Risk Mitigation Accounting proposals are designed to succeed IAS 39 macro hedging, so that accounting follows portfolio-level risk management. We guide banks through the shift.Read the RMA paper→
IFRS 16 leases
Lease valuation and accounting models for IFRS 16 compliance and balance sheet presentation.
PSD3, MiCA and FSMA
Digital asset safeguarding and stablecoin frameworks of best practice, for fintechs and the treasuries that work with them.

Start a conversation

Bring us the hedge that keeps you up at night.

Book a 30-minute diagnostic call. We'll tell you within the hour whether we can help, and where the biggest wins likely sit.

Or email us directly at [email protected]